
United Kingdom – Oil prices jumped on Monday (14) as Saudi Arabia closed a key pipeline amid the Middle East conflict, fuelling worries about high inflation that is set to push the US Federal Reserve into hiking interest rates this week.
As crude futures rose once more – they began the week with gains of three percent – US average diesel prices were also shooting higher, reaching a new record high above $ 6.0 a gallon.
The widely expected Fed hike at a policy meeting set for Wednesday (16) compounded a fresh selloff in technology stocks across Asia but helped strengthen the dollar.
European stock markets were mostly lower around midday, though London managed to advance, helped by gains for heavyweight oil firms Shell and BP as well as its lack of exposure to the technology sector.
Double headache
Tech bosses have backed calls for a slowdown in the development of artificial intelligence amid warnings that the technology could pose a threat to humanity.
Anthropic CEO Dario Amodei was the latest to sound alarm, calling Saturday on AI firms to slow the development of the powerful technology, saying that “addressing the risks requires even more prudence”.
“Oil and AI fears are causing a double headache for investors, with bond yields rising again and a loss of momentum on equity markets,” said Russ Mould, investment director at AJ Bell.
“It adds to existing inflation fears which were stoked last week by the latest US consumer price index data remaining at elevated levels,” he added.
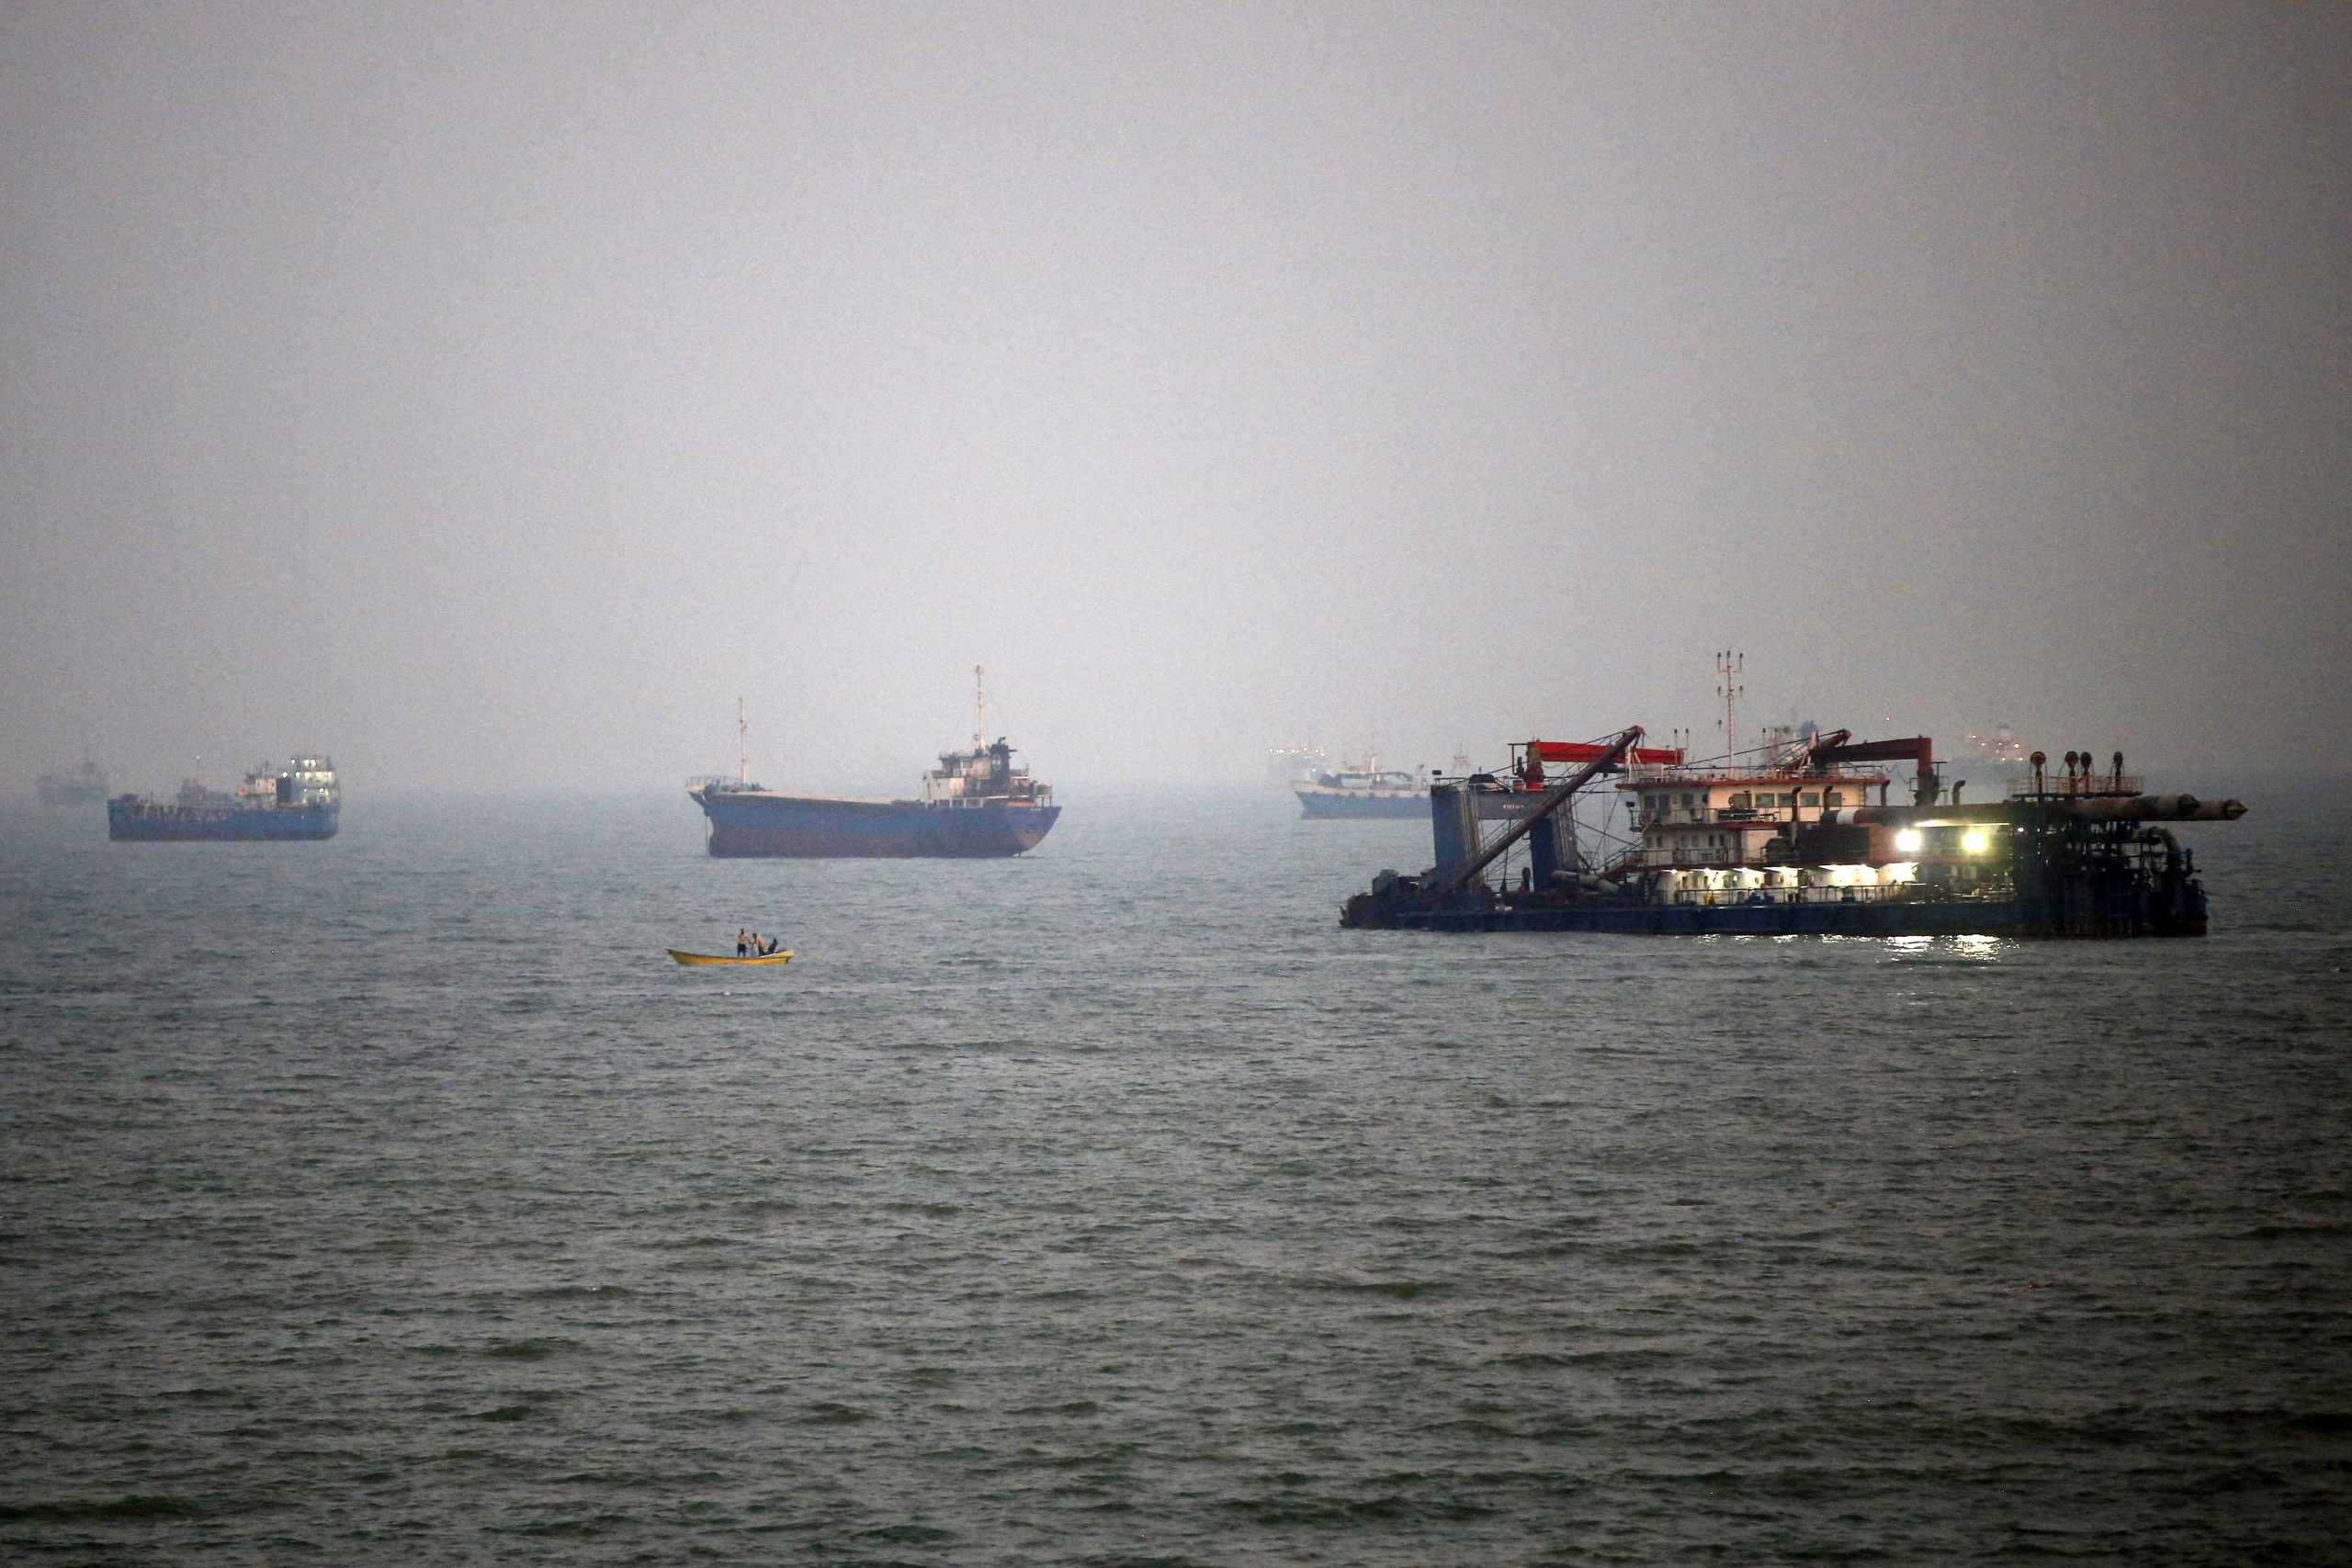
Both main crude contracts – already sitting above $100 a barrel – rallied after Riyadh shut its East-West pipeline following drone attacks by Yemen’s Houthis, while a merchant vessel was struck in the Strait of Hormuz.
At around 10 a.m. this Monday, North Sea Brent crude was up 3.0 percent at $107.71 per barrel, while West Texas Intermediate was up 2.9 percent at $102.90 per barrel.
Reproduction of this content is prohibited.

